Courtesy of Bianca and Charles Boddie
- Bianca and Charles Boddie left lucrative jobs in Seattle to sail and travel in a ‘first retirement.’
- They sold their condo and bought a sailboat, adjusting their lifestyle and finances carefully.
- The couple has no regrets and are now exploring business opportunities and other next moves.
We’d been thriving in Seattle’s tech boom — Bianca, in the US on a work visa, was a senior finance reporter at Business Insider covering how Wall Street’s biggest firms use and invest in technology, and Charlie, a software engineer within Amazon’s payments organization, had spent eight years working toward a principal-engineer role.
We had what people like to call golden handcuffs: good salaries, rising careers, and a sense that if we just kept working hard, we’d likely keep making more money. The handcuffs weren’t all that tight, either; they were actually pretty comfortable.
But for us, quitting our jobs and taking time away from work was a constant if far-off dream. When immigration concerns made our international travel commitments uncertain, we decided not to postpone our dream any longer — and started to look at the numbers.
Our plans began with a spreadsheet
For years, we had saved and invested traditionally: 401(k)s, an apartment that would hopefully appreciate and provide a nest egg for a family home, and some riskier exposure to the stock and bond markets. To leave our jobs, we’d have to figure out how to balance spending during our break without blowing the financial future we’d spent years building.
So we did the thing that makes almost every big life decision feel slightly less terrifying: We put together a spreadsheet. We pegged dollar figures for daily spend, travel, and the boat. Even though they were rough, and there was a sense that the estimates could prove to be way off, putting it down in front of us made it feel real. It also gave us an opportunity to get comfortable with the level of savings we could expect to draw down.
We quit our jobs and took the leap
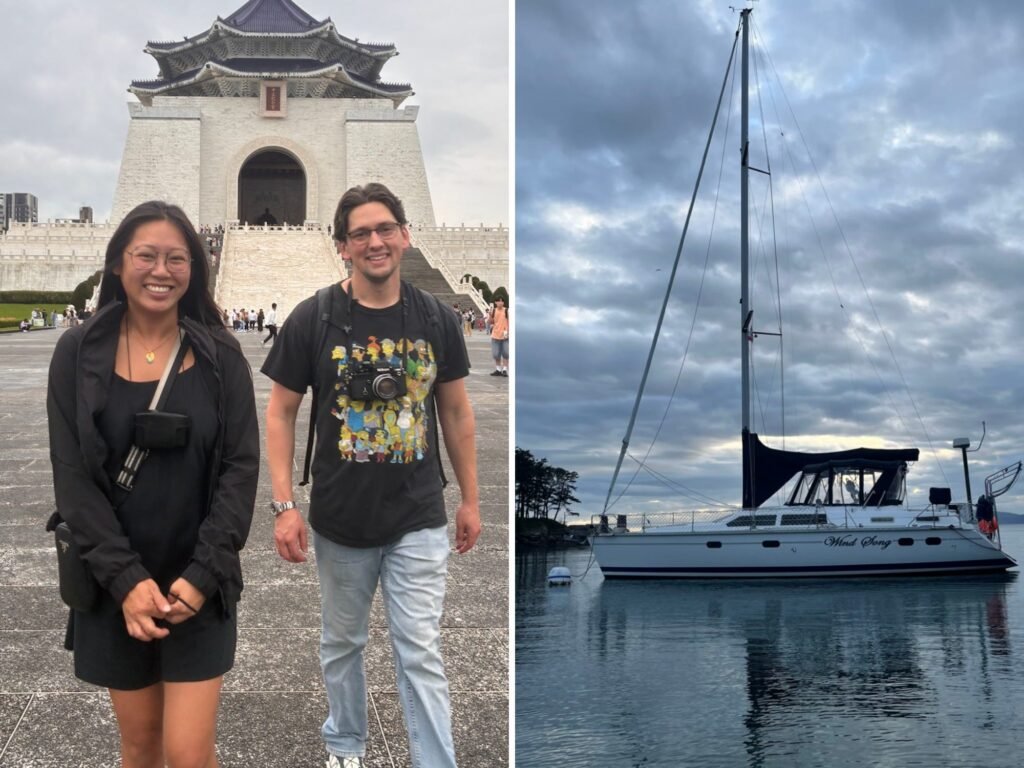
By June 2025, we’d both quit our jobs, sold our Seattle condo, and bought a 42-foot sailboat, Windsong, beginning what we now call our “first retirement.” Almost a year and a half later, we and our dog, Stella, have sailed well over 1,000 miles around the Pacific Northwest, traveled to a dozen countries, and committed more meaningful time towards our families and hobbies.
As it turns out, for us, the hardest part about quitting lucrative jobs wasn’t financial planning for a year and a half without a paycheck. It was getting comfortable with the uncertainty, risk and likely impact on our “final retirement” down the road.
With a bit of budgeting, asset-rearranging, and confidence in ourselves and each other, we were able to make quitting feel like less of a reckless leap and more like a calculated bet on ourselves. For anyone considering such a plan, here’s how we did it.
Courtesy photo
1. We earmarked some savings to be spent
Our budget’s main expenses would be daily living costs, multiple international trips, the purchase of a sailboat big enough to live on for months at a time, and the unpredictable costs of boat ownership (especially unpredictable for us since we’d never owned a boat before).
Until this point, we’d been pretty financially conservative and risk-averse people. We earmarked a portion of our savings we were comfortable saying goodbye to — in return for our travel, boat purchase, and daily living expenses.
This mostly came from Amazon common shares that comprised the majority of Charlie’s compensation and some certificates of deposits that were growing modestly. By diversifying our savings throughout the past eight years, we were able to retain brokerage accounts and 401(k)s, so that we wouldn’t be starting from zero on the backend of our first retirement. It worked out that to achieve our personal goals for this time off work, we would be preparing to spend 10% to 20% of our savings.
Courtesy of Bianca and Charles Boddie
2. We cut our carefree spending
While working, we spent lavishly. That only took a conversation to change.
Right away, we dropped our monthly spending while not away on travel. We achieved this mostly through having fewer fine-dining meals out and being more intentional with bigger purchases, for things like sports tickets and expensive clothing.
While traveling, our spending stayed relatively steady; the point was to travel the way we enjoy with our time off.
3. We dropped our debt and moved in with family
Once we’d made the personal decision of how much savings we were willing to spend, next up was getting rid of our debt. Thankfully, our only debt was the remaining mortgage + HOA costs for our condo — a top-floor, 1400-square-foot unit with sweeping views of Lake Union and the Space Needle.
We’d purchased it in 2022 near the height of the housing market. Now we were in a much tougher real-estate market in Seattle, especially for apartments, and we worried it was a bad time to sell. But our budget wouldn’t work for us with high monthly payments, and the financial liability of being landlords was not something we could stomach.
Luckily, our condo sold promptly for asking price through an off-market deal. We decided to ask family if we could live with them temporarily, when not traveling or on the boat. It would be the first time we were living under the same roof as our families since we were 18. We knew this would not be a sustainable long-term solution for us, but it was key to balancing the budget — and the benefits have been worth it.
Back to budgeting: Our next move
Our break from work has been priceless — but not when we look at what’s left of our nest egg. And when we first quit our jobs, we thought the perfect next step would fall into our lap and we’d know exactly what to do. That hasn’t been the case.
Courtesy photo
For months, we’ve been convinced we want to buy a small business and run it together. We want to be working with our hands, and working for ourselves. We’re starting to evaluate businesses that we think would complement the lifestyle that we want — a marina on an island in southern British Columbia; an inn with 12 cabins we could fix up.
But we’re also starting to itch for a place of our own again and have been tempted by well-designed, and elegantly finished homes nestled in the foothills of Vancouver’s coastal mountain range, homes where we can imagine growing a family in years to come.
With what we have in the bank, we can’t afford both a home and business, and our next step feels very uncertain. Unlike working in a white-collar job, where your next step — a promotion, a new role — is very prescribed, the world now feels like our oyster, and we’re finding it surprisingly hard to be decisive.
Charlie’s dad recently asked us, now that we’re far away from the original decision of quitting our jobs, if we regret it. It’s a good question, especially with the meaningful tradeoffs and the uncertainty about where we go next.
Our answer: 11/10 it was the right move and we still have no regrets.
Bianca and Charlie Boddie were formerly based in Seattle, working as a reporter and software engineer, respectively. Now, they travel and sail around the Pacific Northwest with their dog, Stella, as they enjoy their ‘first retirement.’
Have you made a financial decision or career switch that’s changed your life? Reach editor Debbie Strong at dstrong@businessinsider.com to share your story.